A car loan calculator with tax and fees estimates the payment on the amount you actually borrow, rather than just the sticker price. For a $35,000 car, $5,000 down, 7.5% sales tax and $450 in fees, financing $33,075 at an illustrative 8% annual interest rate for 60 months gives a $670.64 monthly payment and $45,238.53 total purchase cost.
Taxes and fees are hypothetical inputs, not a local quote. Use the free car loan calculator with tax and fees to enter your own numbers, compare terms and inspect the monthly schedule. Calculations run on your device without an account.
How to use the car loan calculator
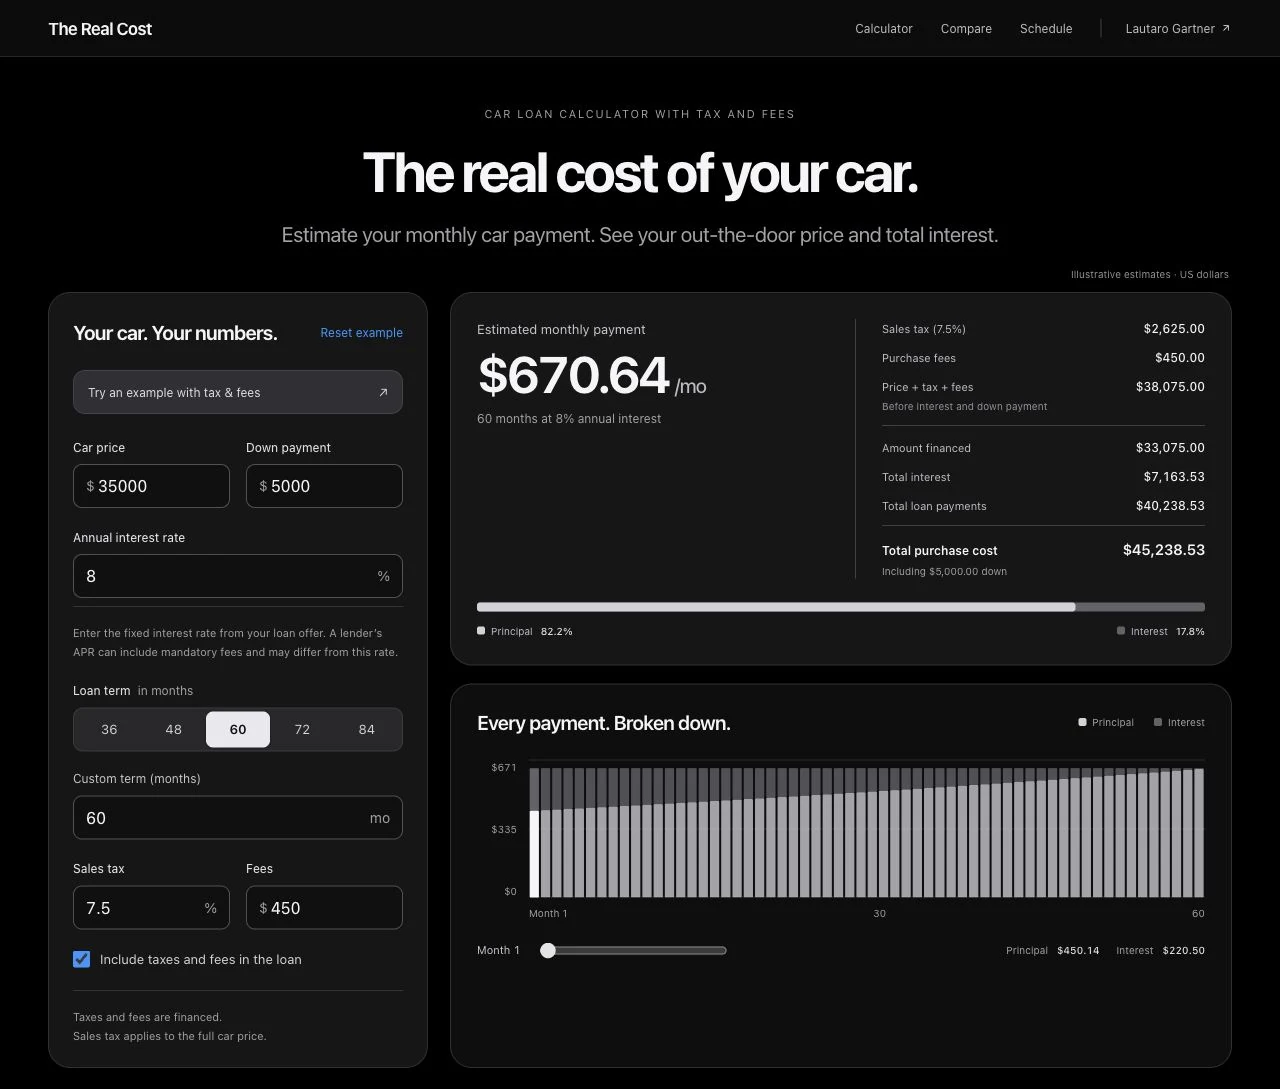
- Enter the negotiated car price. Use the vehicle price before sales tax and separate fees, rather than an advertised monthly payment.
- Add your down payment. This is cash you put toward the purchase. It reduces the amount borrowed.
- Enter the rate and term. Use months: 36 is three years, 60 is five, and 84 is seven. Use the Annual interest rate field for the fixed interest rate in your contract. A lender’s disclosed APR can include mandatory fees and differ from that rate; compare APR disclosures separately.
- Include sales tax and fees. Enter title, registration and dealer fees once. If your quoted price already includes these, separate them before entering the figures so they are not counted twice.
- Choose when to pay those costs. Leave “Include taxes and fees in the loan” checked to borrow them. Uncheck it if you will pay them upfront.
- Read all the results. Check monthly payment, total interest and total purchase cost together. Compare terms, explore the principal/interest chart, and download the amortization schedule as a CSV.
The calculator applies sales tax to the full vehicle price. It does not model local trade-in tax credits, rebates, trade-in equity or an old vehicle’s remaining debt. Ask for an itemized purchase estimate if those apply. Do not put an out-the-door price into the price field and then add the same taxes and fees again.
Compare 36, 48, 60, 72 and 84 months
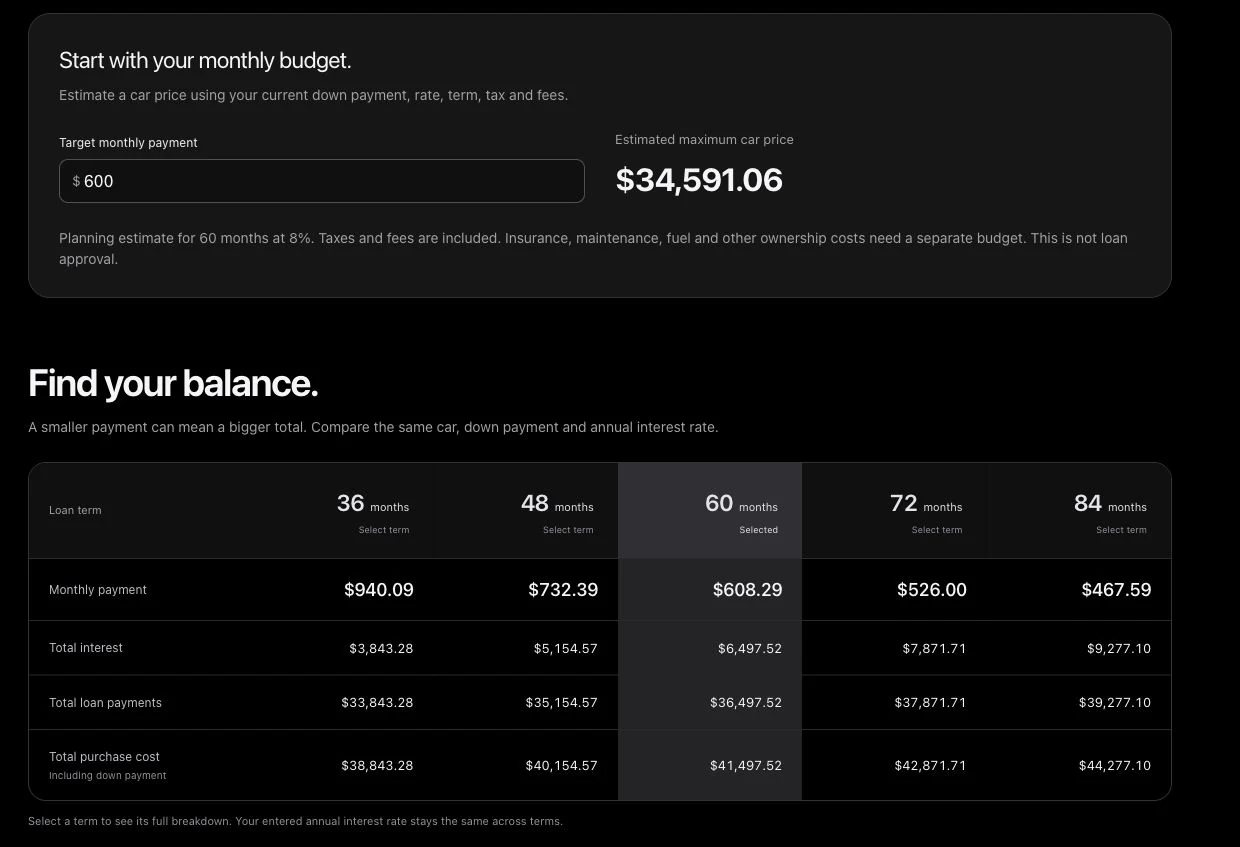
Keep the preset price, down payment and rate fixed. With $30,000 financed at an illustrative 8% annual rate and no tax or fees, the estimated choices are:
| Term | Monthly payment | Total interest | Total purchase cost |
|---|---|---|---|
| 36 months | $940.09 | $3,843.28 | $38,843.28 |
| 48 months | $732.39 | $5,154.57 | $40,154.57 |
| 60 months | $608.29 | $6,497.52 | $41,497.52 |
| 72 months | $526.00 | $7,871.71 | $42,871.71 |
| 84 months | $467.59 | $9,277.10 | $44,277.10 |
The 84-month payment is $472.50 lower than the 36-month payment, but adds $5,433.82 in interest. That is the tradeoff to see before choosing a term. Actual offers may also have different rates for different terms; this comparison deliberately holds your entered rate constant.
If you have a monthly payment limit, use “Start with your monthly budget.” At $600 a month with the preset 8% rate, 60 months, $5,000 down and no tax or fees, the estimated maximum sticker price is $34,591.06. This is a financing estimate, not proof you can afford the car or qualify for a loan. Insurance, fuel and upkeep still need room in your budget.
Loan payments versus total purchase cost
These numbers answer different questions:
- Amount financed: what you borrow. In the original no-tax preset, $35,000 minus $5,000 down leaves $30,000.
- Total loan payments: all scheduled principal and interest payments. The no-tax preset totals $36,497.52. Your down payment is excluded.
- Total purchase cost: all loan payments, plus your down payment and any taxes and fees paid upfront. The no-tax preset totals $41,497.52.
- Out-the-door price before interest: the car price plus taxes and fees. In the no-tax preset it is $35,000. Financing adds $6,497.52 in interest.
Do not add the financed principal to total loan payments: it is already inside them. Do not add financed taxes and fees a second time either. The CFPB explains the main terms on an auto loan disclosure, including amount financed, APR and total payments.
Despite its name, this tool estimates purchase and financing costs. Insurance, maintenance, fuel, depreciation and other ownership costs are excluded. A payment that fits your budget may still leave too little for those expenses.
What happens when you add sales tax and fees?
You either borrow more or pay more cash upfront. In this example, financing tax and fees increases the monthly payment by $62.35 and adds $666.01 in interest. Paying them upfront keeps the loan payment lower but requires $3,075 more cash at purchase.
Try a 7.5% sales tax and $450 in fees on the $35,000 example. Those are hypothetical inputs, not a local tax estimate. Tax is $2,625, so the price including tax and fees is $38,075.
With $5,000 down and costs financed, you borrow $33,075. Over 60 months at the same 8% rate, the calculator estimates $7,163.53 in interest and $45,238.53 total purchase cost.
If you pay the $3,075 tax and fees upfront instead, the loan stays at $30,000 and the regular payment stays at $608.29. You need $8,075 upfront including your down payment. Total purchase cost becomes $44,572.52, including $6,497.52 interest. Financing these costs adds $666.01 of interest in this example.
| Same car and loan term | Monthly payment | Cash at purchase | Total interest | Total purchase cost |
|---|---|---|---|---|
| No tax or fees | $608.29 | $5,000.00 | $6,497.52 | $41,497.52 |
| 7.5% tax + $450 fees, financed | $670.64 | $5,000.00 | $7,163.53 | $45,238.53 |
| 7.5% tax + $450 fees, paid upfront | $608.29 | $8,075.00 | $6,497.52 | $44,572.52 |
All three scenarios use $35,000 price, $5,000 down, 8% annual interest and 60 months. The final payment adjusts for monthly cent rounding.
Which car purchase fees belong in the calculator?
Enter one-time title, registration and dealer documentation fees from the itemized quote. Include a charge only once: an add-on already in the car price should not also go into the fees field. Insurance, maintenance and fuel are separate ownership costs.
For Car price, use the vehicle price before tax and separate fees. If the seller provides an out-the-door total, ask for its price, tax and fee components; entering that total as the price and adding tax again overstates the estimate. Sales tax in this model applies to the full vehicle price, excluding fees.
Tax rules and fee treatment vary. Use the dealer’s itemized quote and the relevant tax authority’s rules. Do not rely on a generic calculator to decide the tax treatment of a trade-in or rebate.
Read your monthly amortization schedule
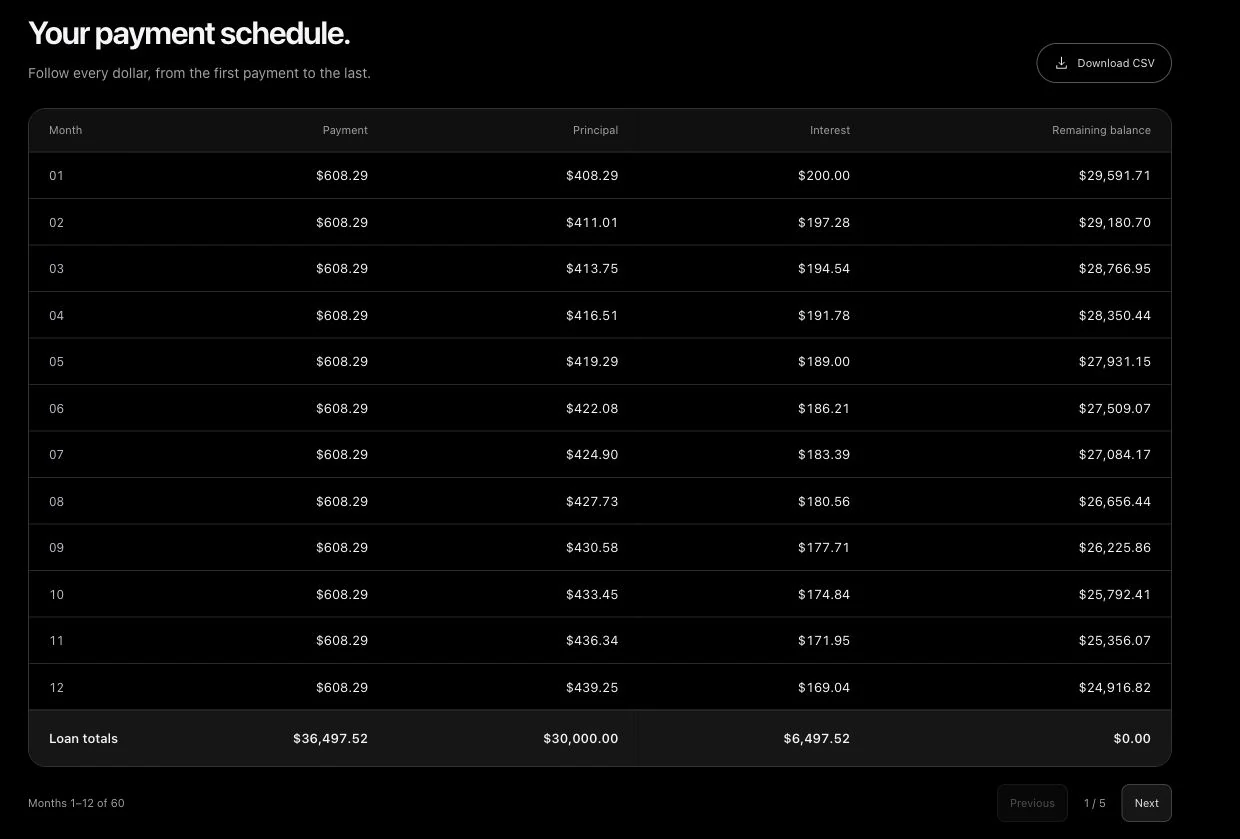
An amortization schedule shows what each payment does: how much pays interest, how much reduces principal, and what balance remains. In month one of the no-tax example:
- Payment: $608.29.
- Interest: $200.00.
- Principal repaid: $408.29.
- Remaining balance: $29,591.71.
Later payments generally contain less interest and more principal because the outstanding balance is smaller. Move through the chart to see the change, then use the monthly table for the exact amounts. Download the CSV if you want to keep a copy or check it in a spreadsheet.
The final payment in the no-tax example is $608.41, rather than $608.29, to clear the remaining cents. Interest is rounded each month. A lender using daily interest, different payment dates or different rounding can produce a different schedule. This table is an estimate, not your contract or a payoff quote.
Questions to answer before choosing a car loan
What is the payment on a $30,000 car loan?
At the illustrative 8% annual rate over 60 months, a $30,000 loan costs $608.29 per month, with an adjusted final payment. A $30,000 car price is different from a $30,000 loan: down payment, taxes and fees change how much you borrow.
Is 72 or 84 months better than 60 months?
It depends on your payment limit and the actual offer. In this example a longer term reduces the monthly payment and increases total interest. Check how long you expect to keep the car and compare the full commitment, rather than treating the lowest monthly number as the cheapest deal.
How much should I put down?
Test an amount you can pay without ignoring your other expenses and cash needs. At the same rate and term, a larger down payment reduces borrowing and interest. The calculator shows the effect; it does not set a universally appropriate deposit or decide affordability for you.
Does 0% interest mean the car has no extra costs?
No. At 0% in this model, the loan has no interest, but taxes, fees and your down payment still count. For example, $30,000 financed over 60 months is $500 a month at 0%. Check any conditions attached to a real promotion separately.
Which interest rate should I enter?
Use the rate in your actual offer when available. Enter the contract’s fixed annual interest rate. The calculator divides that rate by 12 for monthly calculations. A disclosed APR can incorporate mandatory financing charges and differ from the contract rate. Compare the lender’s disclosure separately and avoid counting a financing fee twice. The preset 8% is not a prediction of your rate.
Can I estimate a used car payment or an existing loan?
Yes, the same fixed-rate calculation can estimate a used-car payment with your own price and offered rate. For an existing balance, set price to that balance, down payment to zero, tax and fees to zero, and use the remaining months. Early payoff fees, refinancing charges and daily-interest adjustments are not modeled.
A short checklist before you commit
Get the itemized price, rate, term, down payment and fees in writing. Match those to your estimate. Compare the same purchase across offers, including total interest and total payments. Allow separately for ownership costs, and check the actual loan disclosures before signing.
For more context, see the CFPB guide to comparing auto loan offers beyond the monthly payment.
Calculate your car payment and compare loan terms
This guide was written by Lautaro Gärtner, who created the calculator. Updated November 3, 2026. All numerical examples use this tool’s stated fixed-rate assumptions; they are not lender offers or personalized financial advice. The page images are actual calculator screenshots. The calculation is covered by unit tests; the source is available to inspect.